A ceiling stain after a storm can feel like a clear insurance claim. But roof leak insurance exclusions often determine whether the insurer pays for repairs, pays only part of the loss, or denies the claim entirely. The key question is rarely just, “Is there water inside?” It is usually, “What caused the water to get in, and what condition was the roof in before the storm?”
For homeowners and property managers, that distinction matters. A covered wind event may damage shingles, flashing, vents, or roof decking and allow water into the building. On the other hand, a leak caused by years of wear, an old failing pipe boot, or deferred maintenance may fall outside the policy. Knowing the difference early helps you protect the property, document the damage correctly, and avoid avoidable surprises during the claims process.
Why the Cause of the Leak Matters Most
Most property insurance policies are designed to cover sudden, accidental damage caused by a covered event. Wind, hail, falling trees, and certain storm-related impacts may be covered perils, subject to your deductible and the language in your policy.
A roof leak is not always the covered event itself. It is the result of something else. If a windstorm lifted shingles and rain entered through the newly exposed area, the storm damage may support a claim. If rain entered through cracked, brittle shingles that had been deteriorating for years, the carrier may classify the issue as maintenance-related.
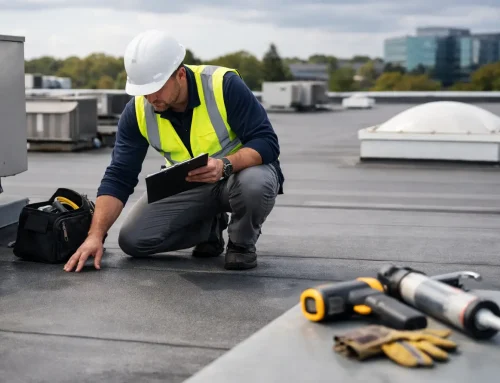
This can be frustrating because the interior water damage may appear identical in both situations. A professional inspection can help identify whether there are storm-created openings, creased or missing shingles, hail impacts, damaged flashing, punctures, or other evidence connected to a recent event. Photos taken before temporary repairs are especially valuable.
Common Roof Leak Insurance Exclusions
Insurance policies differ by carrier, state, property type, and endorsement. Still, several exclusions appear frequently in roof-related claims.
Wear, tear, and age-related deterioration
Normal aging is one of the most common reasons a roof leak claim is denied. Shingles eventually lose granules, become brittle, curl, crack, or fail around penetrations. Sealants dry out. Flashing can corrode or pull away over time. Insurance is not generally intended to pay for routine replacement when materials reach the end of their expected life.
That does not mean an older roof can never have a covered claim. An older roof can still sustain sudden wind or hail damage. It does mean the insurer may look more closely at whether the storm caused the opening or merely revealed a condition that already existed.
Deferred maintenance and neglect
Policies commonly exclude damage resulting from failure to maintain the property. Examples can include allowing debris to collect in roof valleys, ignoring loose flashing, failing to repair a known leak, or leaving damaged shingles exposed through multiple weather events.
If you have noticed a small stain for months and it spreads after a storm, the insurer may separate old, ongoing damage from new storm-related damage. Prompt action matters. Addressing a minor issue early can prevent larger repair costs and strengthen the record that you acted responsibly once damage was discovered.
Faulty workmanship or defective materials
A policy may exclude the cost to correct improper installation, defective shingles, poor flashing details, or other construction defects. For example, if a roof leaks because flashing was installed incorrectly years ago, the cost to fix that workmanship issue may not be covered.
There can be an important distinction here: while the defective component itself may be excluded, some policies may treat resulting damage differently. Coverage for ensuing water damage depends on the policy wording and the facts of the loss. Do not assume either outcome. Read the policy and ask the adjuster for a written explanation of the coverage decision.
Repeated seepage or long-term water damage
Many policies exclude water damage that happens gradually or repeatedly over weeks, months, or longer. Slow leaks behind drywall, around a chimney, or near a skylight can create rot, mold, insulation damage, and stained ceilings before anyone sees the problem.
A storm can make a long-term leak more noticeable, but that does not automatically make the full damage storm-related. Documentation from an inspection can help distinguish fresh damage from deterioration that developed over time.
Flooding, surface water, and water backup
Water entering through a damaged roof is different from floodwater entering from the ground. Standard homeowners and commercial property policies typically treat flood losses separately. Water backup from drains, sewers, or sump pumps may also require a specific endorsement.
During severe storms, a building may have more than one source of water intrusion. The ceiling leak may be roof-related, while lower-level water damage may involve surface water or backup. Identifying every source accurately helps prevent confusion in the claim.
Mold, rot, and code upgrade limits
Mold remediation, rot repair, and building code upgrades may have special limits or exclusions. A policy could cover some direct water damage but limit how much it pays for mold treatment. Likewise, bringing part of a damaged roof up to current code may require ordinance or law coverage.
These details become especially significant on older homes and commercial buildings. Before approving a scope of work, review the estimate alongside your policy limits, deductible, and any applicable endorsements.
A Leak After a Storm Does Not Always Mean a Full Roof Replacement
A covered loss does not automatically mean the insurer will approve a full roof replacement. The decision depends on the damage pattern, repairability, local code requirements, matching considerations, policy terms, and the roof’s condition before the event.
For example, several missing shingles on one slope may be repairable. Widespread wind creasing across multiple slopes may support a broader repair or replacement scope. Hail damage can be more difficult to assess from the ground because impacts may affect the shingle mat even when the roof does not look severely damaged at first glance.
Actual cash value and replacement cost coverage also matter. Actual cash value policies generally account for depreciation, while replacement cost coverage may pay additional amounts after qualifying work is completed. Both may still be subject to deductibles, exclusions, and limits. The declarations page and policy form provide the answer for your property.
What to Do When You Find a Roof Leak
Your first responsibility is to prevent additional damage when it is safe to do so. Move furniture and valuables away from the affected area, catch dripping water, and photograph the interior before removing damaged materials. If water is collecting in a ceiling, avoid standing beneath a sagging area and contact a qualified professional promptly.
If the roof is actively leaking after wind, hail, or a fallen limb, emergency tarping may be necessary. Keep invoices and take photos of temporary protection measures. Reasonable mitigation is often expected by insurers, and it can prevent a small opening from becoming widespread interior damage.
Next, document what you know: the date and time you noticed the leak, the weather event, photos of the exterior and interior, video of active dripping if possible, and receipts for emergency services. Do not throw away damaged materials until your insurer has advised you or the claim has been documented.
Then report the claim to your insurance carrier. Describe the facts without guessing at the cause. A clear statement such as, “After the windstorm on Tuesday, we found water entering through the living room ceiling,” is more useful than assuming the roof needs replacement before an inspection has occurred.
How an Inspection Supports a Clearer Claim
A thorough roof inspection is not about forcing a claim. It is about establishing the condition of the property and identifying damage that may not be visible from the ground. A qualified contractor can document affected roofing components, exterior elevations, gutters, siding, and interior areas that may be connected to the event.
That documentation gives you a practical basis for conversations with the adjuster. It can also identify situations where a repair is the honest recommendation, even if the homeowner initially feared a full replacement. If the insurer’s scope misses documented damage or uses an unclear repair approach, ask questions and request that the basis for the decision be explained.
Crown Exteriors helps property owners inspect storm damage, document findings, and communicate clearly through the restoration process. The goal is straightforward: protect the property, support an accurate claim, and complete the right repair with quality workmanship.
Review Your Policy Before the Next Storm
The best time to understand exclusions is before water reaches the ceiling. Review your deductible, roof settlement type, wind and hail provisions, ordinance or law coverage, mold limits, and any endorsements that affect water damage. Commercial property managers should also review business interruption and tenant-related responsibilities with their insurance professional.
Keep dated photos of your roof and exterior after maintenance or replacement. Save invoices for repairs, gutter cleaning, and inspections. These records cannot change an exclusion, but they can show that the property was maintained and help establish its pre-loss condition.
When a storm leaves you unsure whether the leak is old, new, or covered, do not wait for the stain to grow. A timely inspection and temporary protection can preserve both your building and the facts needed to make the next decision with confidence.
Related Posts
If you enjoyed reading this, then please explore our other articles below: